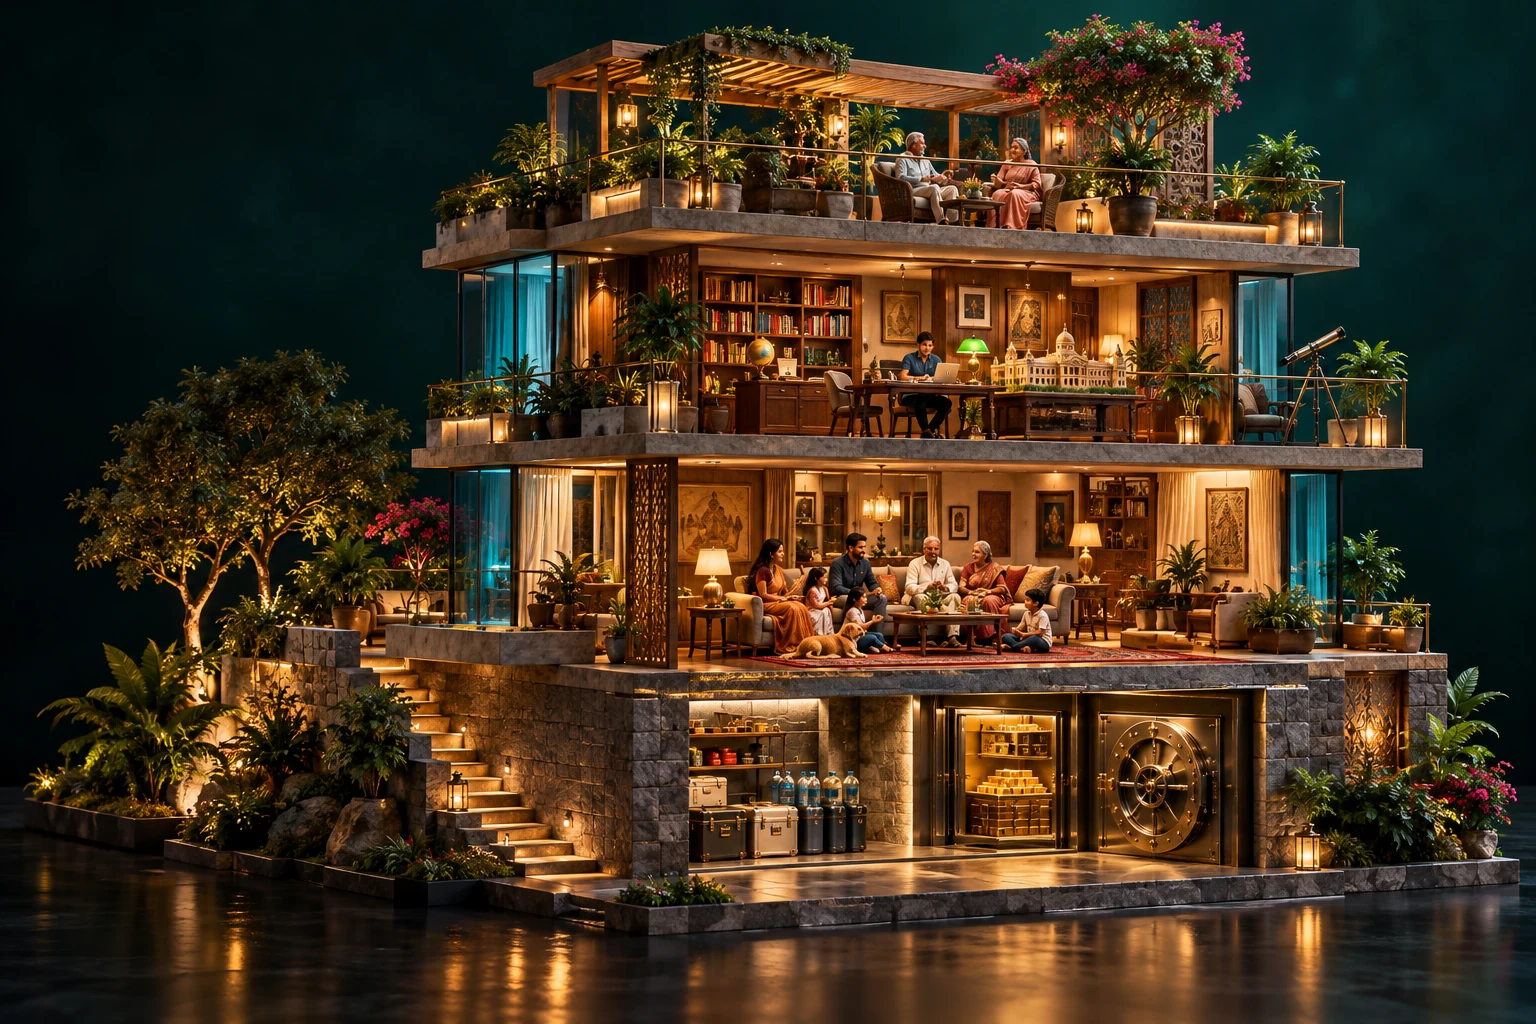
Family money rarely has one job. The same household may be protecting this year’s school fees, preparing for a home deposit, supporting parents and building retirement resilience at the same time. A goal map makes those competing horizons visible before products enter the discussion.
The architecture of a financial life
Walk through the layers of your plan.
Select a floor. Each opens a different conversation about the money your household needs.01 · Foundation
Start with what must hold.
Before discussing distant goals, map the obligations that continue when income is interrupted. List essential expenses, existing protection and accessible money. The illustration is a metaphor; it is not a prescribed allocation.Start with roles, not a single portfolio number
Begin by naming what each pool of money may need to do. Immediate reserves protect ordinary life from disruption. Known payments need dependable access. Longer goals may have more time to absorb uncertainty, but their dates and importance still differ.
A family conversation should include the people affected by the plan. Income stability, dependants, existing debt, insurance, health needs and the possibility of supporting older relatives can change how much flexibility a goal really has.
- Which household expenses cannot be postponed?
- Which goals have a fixed date, and which can move?
- Who would need to act if the primary financial decision-maker were unavailable?
A fictional family map, expressed in today’s rupees
Illustrative values — not targets
These amounts describe one fictional household for layout and planning discussion. They are not suggested goal amounts or product allocations.
Compare the job, date and flexibility of each goal
A comparison of four fictional family goals, their timing, flexibility and the first planning question each raises.
| Goal | Today’s estimate | When needed | Date flexibility | First question |
|---|---|---|---|---|
| Emergency reserve | ₹6 lakh | Available now | Low | How quickly can it be accessed? |
| Home deposit | ₹15 lakh | Around 5 years | Medium | Could the purchase date move? |
| Education | ₹18 lakh | Around 10 years | Low near the date | How will the estimate be updated? |
| Retirement income | Not yet estimated | 20+ years | Varies | What monthly household income may be needed? |
Amounts are fictional present-cost estimates. Inflation, taxes, fees, borrowing costs and changing family circumstances are excluded.
Keep the life behind the numbers visible
A useful goal map is specific enough to support decisions but flexible enough to change with the household. Review the purpose, amount and date when income, dependants or priorities change—not only when markets move.
Protect the foundation before stretching the horizon
Sources and assumptions
Assumptions and limits
- The family, goal amounts and dates are fictional and shown only to demonstrate a planning structure.
- All rupee amounts are present-cost estimates; no inflation, return, tax, fee or product assumption is applied.
- The framework is educational and does not determine suitability or replace a complete household review.
Disclosures
- Investor information for general educational use; not personal financial advice.
- Illustrative or hypothetical figures are identified with their assumptions and are not actual performance.